

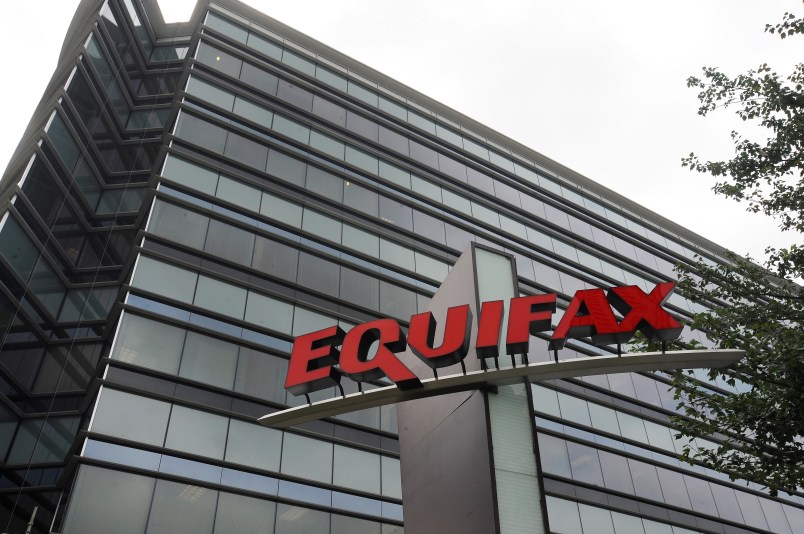
NEW YORK (AP) — Investors were bailing out on Equifax a day after the credit monitoring company said a data breach exposed the Social Security numbers and other personal data of 143 million Americans.
Equifax shares fell about 13 percent to $123.75 in heavy trading. The decline equates to about $2.28 billion in lost market value.
The company is one of three major U.S. credit bureaus, the declines extended to its competitors. TransUnion fell 4 percent and Experian stock declined 1 percent in London.
Lenders rely on the information collected by the credit bureaus to help them decide whether to approve financing for homes, cars and credit cards. Credit checks are even sometimes done by employers when deciding whom to hire for a job.


As Josh pointed out on Twitter: “Who would we rely on to collect erroneous, unconfirmed or fraudulent info that damages us through no fault of our own?”
One of the wisest investors I know described his approach to investing in the stock market:
“I’ll start buying when the insiders stop selling.”
Speaking of insiders, the staff, no not Cruz’s, were bailing a few days before the announcement. Funny how that is.
Senator Heidi Heitkamp, a North Dakota Democrat who sits on the Senate Banking Committee, said it was “disturbing” that it appeared executives sold nearly two million dollars’ worth of company stock in the gap between learning of a sweeping hacker intrusion and making it public.